Nvidia's Huang Resigns, Tech Stocks Drag Market
Published as of: November 12, 2026, 9:12 a.m. ET
Listen to this article
Listen here or subscribe to the Schwab Market Update in your favorite podcast app.
| The markets | Last price | Change | % change |
|---|---|---|---|
| S&P 500® Index | 7,619.38 | +98.45 | +1.31% |
| Dow Jones Industrial Average® | 52,486.49 | +254.60 | +0.49% |
| Nasdaq Composite® | 25,466.19 | +400.31 | +1.60% |
| 10-year Treasury yield | 5.05% | +0.06 | -- |
| U.S. Dollar Index | 102.92 | +0.01 | +0.01% |
| Cboe Volatility Index® | 18.74 | +1.25 | +7.15% |
| Gold | $3,912.10 | -$89.10 | -2.24% |
| WTI Crude Oil | $86.88 | +$0.35 | +0.37% |
| Bitcoin | $72,680 | -$2,045 | -2.74% |
(Thursday market open) Jensen Huang resigned as Nvidia's (NVDA) CEO today after the New York Times reported he'd engaged in an extramarital affair with an executive at his company. This followed him admitting an affair with a woman alleged to be a Chinese spy. The tech-focused Nasdaq Composite fell more than 1% on the news, dragging other indexes, and Nvidia said Chief Financial Officer Colette Kress will serve as interim CEO and remain CFO while the board searches for Huang's replacement.
Nvidia fell 10% early, extending previous losses, and is down 30% from its October 6 peak, wiping out hundreds of billions of dollars in market capitalization. Nasdaq's Nvidia-driven stumble came just a day after the chip market appeared to pick itself off the floor thanks to solid results from CoreWeave (CRWV). Another "neocloud" firm, Nebius (NBIS), reported this morning, with key earnings due from Cisco (CSCO) and Applied Materials (AMAT) after the close.
Major indexes climbed broadly Wednesday, led by chips, but consumer stocks were subdued after Tuesday's inflation-focused Treasury yield rally. "CoreWeave delivered a 'beat and raise quarter' and beat on incrementally improving margins, which sends the signal that there's still excess demand for compute," said Nathan Peterson, director of derivatives research and strategy at the Schwab Center for Financial Research (SCFR). In data today, weekly initial jobless claims edged up to 200,000, still historically low.
To get the Schwab Market Update in your inbox every morning, subscribe on Schwab.com.
Three things to watch
- Nvidia deeper dive: Before Huang's announcement, Nvidia received downgrades this morning from Bernstein, William Blair, and Oppenheimer. Analysts think even with Huang out of the CEO suite, continued investigations into his relationship with the alleged Chinese spy could overhang shares. The investigation might take months, extending the risk of damaging headlines. They point out the company has no succession plan and may struggle to execute amid what could be negative sentiment within the firm and more intense competition from other chip companies that smell blood in the water. There might also be ramifications for Nvidia's business if the U.S. government enforces tighter restrictions on sales of its products—not only to China but to other parts of Asia. Nvidia has tapped an outside firm to find a permanent replacement, Bloomberg reported. At its peak, Nvidia's market capitalization topped $5 trillion and represented about 7% of the S&P 500's value. Huang, who founded Nvidia 33 years ago, was the public face of the entire AI boom.
- CPI breadth test: One doesn't often hear adjectives like "borderline disturbing" from a Federal Reserve official. But Chicago Fed President Austan Goolsbee told PBS that this week regarding the October Consumer Price Index (CPI), which rose 0.4% monthly. Dallas Fed President Lorie Logan also made hawkish remarks. With inflation stubborn, the Fed may be focused on CPI breadth, or the percentage of prices that are climbing 3% or more per month annualized. In August, Fed Chairman Kevin Warsh pointed to the breadth of price increases, which then showed 50% of items in the Fed's preferred inflation basket rising faster than 3%. For CPI, that percentage is now 54.4%, up from the two-decade average of one-third. So-called "super-core CPI"—or core services excluding housing, food, and energy—is above 0.4% monthly, hinting that inflation from energy is breaking through. The October Producer Price Index (PPI) at 8:30 a.m. ET tomorrow is seen at 0.4% for headline and 0.3% for core, down from September's parabolic 1.3% and 0.7%. Core excludes food and energy. No annual figures will be available due to last year's government shutdown.
- Key tech earnings up next: Applied Materials and Cisco report later today, wrapping up a busy week of tech earnings before reporting season shifts to retailers next week. Shares dropped initially when Applied Materials last reported, despite strong sales guidance. This could have reflected elevated investor expectations for the semiconductor equipment firm, Reuters reported then. The company's fortunes depend heavily on the AI infrastructure buildout, making it a good barometer. Cisco, a giant networking company with tentacles across the global tech business, forecast strong revenue last time it reported in August, but shares dropped despite that and solid results. The company said then it saw its highest productivity metrics in 30 years, a factor that might be worth watching today for signs of AI's impact. It guided then for fiscal first quarter revenue between $18 billion and $18.2 billion. Analysts expect Cisco to report earnings per share of $1.33, up 32.6% annually, and revenue of $18.1 billion, up 21.8%.
Crypto currents
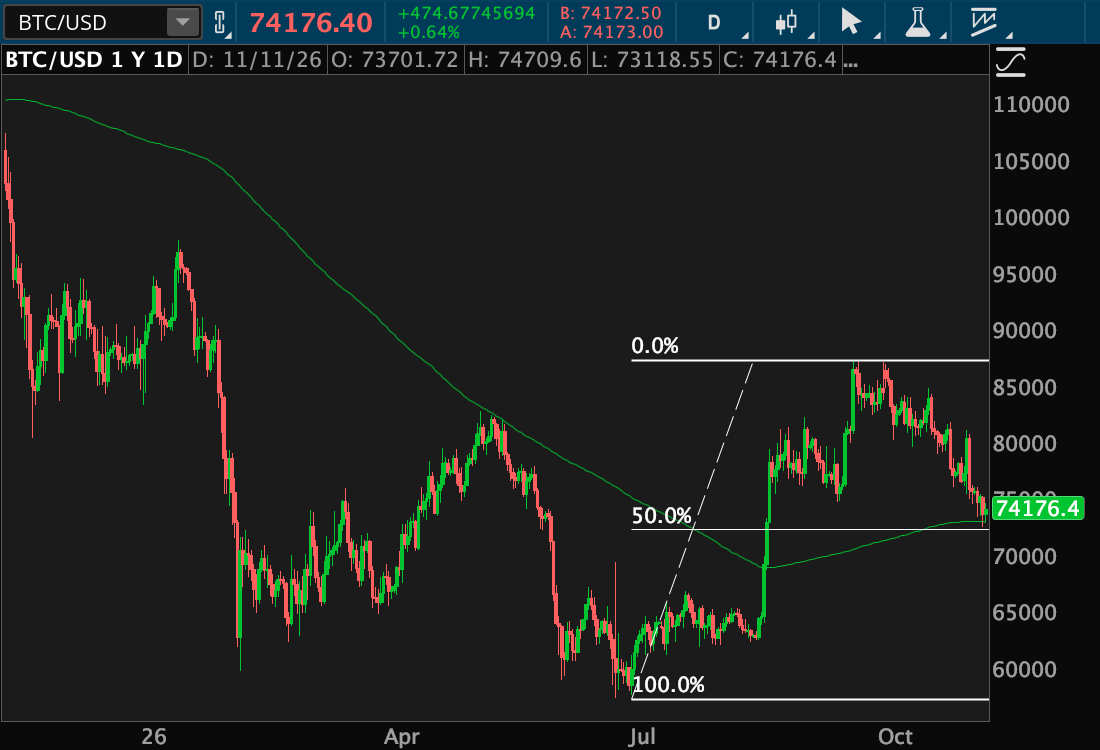
Bitcoin slides as fund outflows rise: Short-term bitcoin holders are being tested as the coin grinds lower. Bitcoin has retraced about 50% of its July-September rally, and on Wednesday afternoon sat just above its 200-day moving average, trading for about $74,400. That's below the average price of $75,600 paid by short-term (under 155 days) holders, according to Glassnode. As a result of the recent slide, only about 35% of short-term holders are now sitting on a profit, versus "nearly all" who were in the black at the September high. One thing to watch for is whether they use a potential rally to get out at around breakeven, or whether they cut their losses if price slides further, adding fuel to the selling. Meanwhile, bitcoin exchange-traded products (ETP) have seen selling pick up, with the 30-day average net outflows hitting the highest level since July as of Tuesday. Recent outflows remain relatively mild, though, and total flows since July 1 remain net positive.
On the move
- Nebius slid 14% early despite reporting earnings and revenue above analysts' consensus. Its quarterly loss of $0.13 per share was $0.59 better than FactSet's consensus. However, its revenue outlook disappointed and investors appeared concerned about heavy spending by the company. Though Nebius, like CoreWeave, is a "neocloud" firm, its business differs from CoreWeave's in many ways. And like CoreWeave, it has business ties to Nvidia.
- Other chip and AI-related stocks mostly turned lower early after yesterday's surge, with the exception of Advanced Micro Devices (AMD) and Broadcom (AVGO)—two direct competitors of Nvidia expected to potentially benefit from their larger rival's struggles. AMD rose 1.5% after an upgrade by William Blair to outperform from market perform.
- Stocks under pressure early in the AI sector beside Nebius included Sandisk (SNDK) off 6%, Super Micro Computer (SMCI) backtracking almost 6%, and Applied Digital (APLD) down more than 5%. CoreWeave is down 10% after spiking almost 26% on Wednesday following earnings, hurt by a Bloomberg report that the company is weighing a $4 billion investment-grade loan offering.
- AI-adjacent companies including Dell (DELL) and Bloom Energy (BE) both suffered from their association early, down 4% each.
- Hims & Hers Health (HIMS) dropped 4% ahead of the open after earnings disappointed.
- Strategy (MSTR) plunged 6.7% before the open after Reuters reported that index operator MSCI will remove Strategy and other companies from its global indexes, saying such companies have "fund-type characteristics."
- Health care and staples stocks rose early as investors appeared to enter "risk-off" mode.
- Gold fell 1.4% early, hurt by a rising dollar as Fed rate hike odds for next month stayed at 100%, according to the CME FedWatch Tool.
- Magnificent Seven members Meta Platforms (META), Microsoft (MSFT) and Amazon (AMZN) wilted Wednesday, possibly on concerns that the strong demand cited by CoreWeave could keep chip and AI component prices elevated. Microsoft continued to face pressure amid concerns it could suffer competition from Anthropic.
- Consumer stocks under pressure Wednesday included a score of household names like McDonald's (MCD), United Airlines (UAL), and Gap (GAP). Rebounding yields and crude prices this week likely weighed, as did the rotation back into tech.
- Existing home sales for October are due at 10 a.m. ET. Consensus is for a slight drop to 3.94 million on a seasonally adjusted annual basis, according to Briefing.com. That compares to 3.99 million in September.
More insights from Schwab
IPO investing at Schwab: Our step-by-step guide on Schwab's IPO investing process covers everything from start to finish, including key steps like reviewing the prospectus and submitting an indication of interest. IPOs have been in the news a lot lately, but they do come with risks.
What's next in Washington: The midterm elections dramatically shifted the balance of power to Congressional Democrats. A development that begs the question … now what? The latest episode of the WashingtonWise podcast digs into what the new Congress will face and what it may try to achieve despite a divided government.
Probing investor trends: The October Schwab Trading Activity Index™ (STAX)—which analyzes Schwab client activity to gauge investor sentiment—saw every generation post a record score, led by Gen X, while AI-linked tech stocks accounted for nearly all the top buys. Learn more about what went on under the surface in our STAX Trends Update.
Post-earnings options strategies: Stocks can behave in mysterious ways after an earnings announcement, and what seems like a lasting rally or sell-off may be short-lived. Our newest trading article shares how options traders might use speculative strategies in a post-earnings environment.
Tough decisions during a tougher time: After losing a parent, the last thing you want to worry about is money. But sometimes financial decisions come quickly and are unavoidable. Here are some tips for soldiering through.
Chart of the day
Data source: CME Group. Chart source: thinkorswim® platform.
Past performance is no guarantee of future results.
For illustrative purposes only.
The Fibonacci retracement tool (white lines) shows that bitcoin (BTC/USD—candlesticks) has now retraced about 50% of the move it made from early July through late September, pulling back to a level that coincides with the 200-day moving average (green line).
The week ahead
Thursday, November 12: October existing home sales and expected morning earnings from Brookfield (BN) and Nebius (NBIS). Expected afternoon earnings from Cisco (CSCO) and Applied Materials (AMAT).
Friday, November 13: October PPI and core PPI.
Monday, November 16: Expected morning earnings from Baidu (BIDU) and Tyson Foods (TSN).
Tuesday, November 17: October retail sales, October industrial production and capacity utilization, and expected morning earnings from Home Depot (HD) and Walt Disney (DIS), and afternoon earnings from Nvidia (NVDA).
Wednesday, November 18: October housing starts and building permits, FOMC minutes, and expected morning earnings from TJX (TJX), PDD Holdings (PDD), Lowe's (LOW), Target (TGT), and Williams-Sonoma (WSM). Expected afternoon earnings from Palo Alto Networks (PANW).
Thursday, November 19: Leading Economic Indicators for October from Conference Board, and expected morning earnings from Walmart (WMT), Alibaba (BABA), and NetEase (NTES). Expected afternoon earnings from Intuit (INTU), Ross Stores (ROST), and The Gap (GAP).